

Wallet: Budget Expense Tracker
4.6

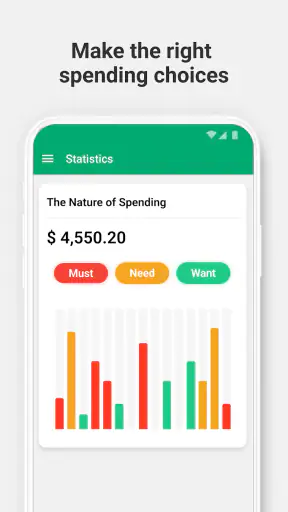
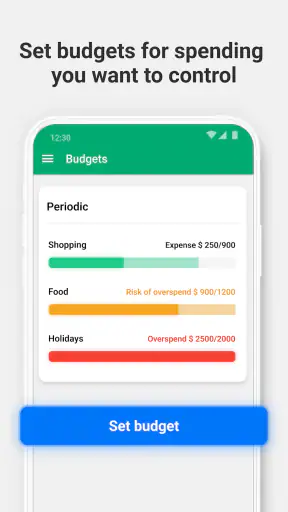
I have always found that managing money becomes difficult at the exact moment life gets busy. A few card payments, a bill moved to a different day, and a handful of small purchases can make a monthly budget feel unclear. Wallet: Budget Expense Tracker approaches that problem as a finance app from BudgetBakers, giving me one place to organize spending, bills, and savings instead of relying on memory or a collection of notes.
After using it as a daily money companion, my impression is that it works best when I treat it as a routine rather than a magic fix. The app can make financial patterns easier to see, but the quality of those patterns depends on how consistently I record and review them. That balance is important: Wallet is most useful when it turns regular attention into a simple habit, not when I expect it to manage every decision for me.
How Wallet fits into everyday money management
Wallet: Budget Expense Tracker is a free finance app for Everyone, and BudgetBakers has been developing it since Apr 21, 2011. Its current version is 9.3.6, with a minimum operating system requirement of 8.1. Those details make it accessible to people using a broad range of Android devices, while the free entry point means I can explore the basic experience before deciding whether I want to spend anything.
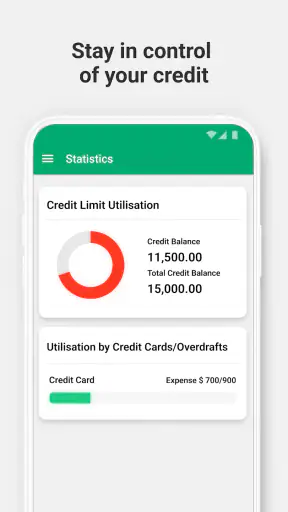
The app’s role is broader than a simple expense notebook. I can use it to bring together everyday spending, upcoming bills, budget planning, and savings goals in one financial view. That combination matters because a budget is not only about recording what has already happened. It is also about seeing what is due next and understanding how today’s choices affect the rest of the month.
Wallet has built a substantial audience, with an average rating of 4.6 from roughly 384 thousand ratings and more than 10 million installs. That does not guarantee that every user will enjoy the same workflow, but it does suggest that the app has found a practical place in many people’s financial routines. I would still judge it by the way I personally handle money, because an app that suits a careful planner may feel unnecessarily detailed to someone who only wants a quick monthly total.
What the free starting point really means
The app is free to download, which is the most important cost detail for someone deciding whether to try it. I can begin without committing money upfront, test whether its organization style makes sense to me, and decide later if additional paid value is worthwhile. That is a better starting position than paying before I know whether manual tracking, budgeting, and bill organization fit my habits.
There are in-app purchases ranging from $0.99 to $144.99 per item. I see that range as a reason to examine any upgrade carefully rather than assuming every paid option is automatically good value. The free access lowers the risk of experimenting, but the presence of purchases means I would check exactly what a selected option adds and whether I would use those additions repeatedly.
In practical terms, the free version is most attractive to someone who wants to learn the workflow first. If I only need a lightweight spending log, I can decide whether Wallet feels clearer than a spreadsheet or a basic notes app. If I want a more involved financial system, the purchase range makes it especially important to separate a genuinely useful long-term feature from something that merely looks appealing during setup.
Recording spending without losing the bigger picture
The central strength of Wallet is the connection between individual transactions and broader financial planning. Entering a coffee, transport fare, subscription, or grocery trip is not very valuable by itself. It becomes useful when those entries are grouped into a picture that helps me understand where money is going and what remains available for the rest of the period.
I recommend beginning with a small number of categories that match real decisions. If I create too many labels immediately, recording becomes a chore and I start postponing it. A simpler structure lets me answer useful questions quickly: am I spending more on eating out than expected, are recurring bills crowding out flexible money, and is a savings target realistic after essentials are covered?
One non-obvious benefit of this approach is that it separates awareness from judgment. I do not need to label every purchase as good or bad. I can first make the pattern visible, then decide what deserves adjustment. That makes the app more helpful for people who want honest information about their habits without turning every transaction into a moral decision.
Bills and timing are where the app becomes more practical
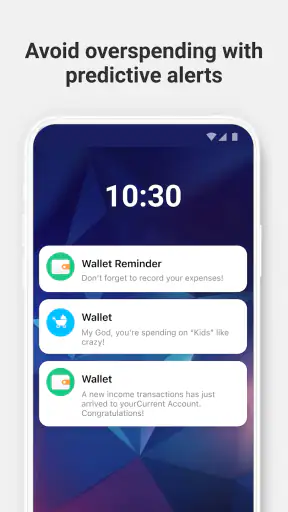
A monthly total can look comfortable while a badly timed bill creates a short-term problem. Wallet’s focus on bills gives the budget a calendar dimension: I can think about what is due, not just what I have already spent. That is particularly useful when income and expenses arrive on different days or when several recurring payments are spread across the month.
For example, imagine I receive income near the middle of the month while rent, utilities, and a subscription are due earlier. A simple expense list may tell me how much I spent last month, but it does not automatically make the timing feel manageable. In Wallet, I can review the upcoming obligations alongside current spending and avoid treating the full account balance as freely available money.
My practical tip is to review bills before setting a flexible spending limit. Otherwise, I may allocate money to restaurants or shopping and only later remember that a fixed payment is approaching. The app is more valuable when I use it for this forward-looking check, because it helps distinguish money that is technically present from money that is genuinely available.
Using the app for a realistic savings routine
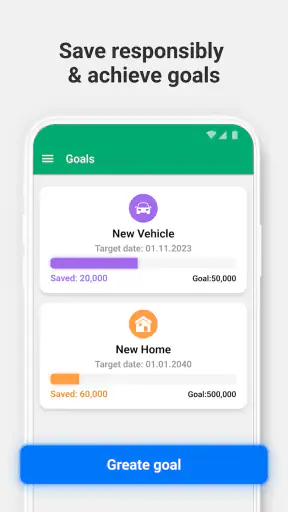
Savings planning often fails because the target is disconnected from ordinary spending. Wallet is more useful when I set a goal after looking at actual bills and recurring costs rather than choosing an ambitious figure first. The sequence matters: understand obligations, observe flexible spending, then decide what can be moved toward savings without creating a stressful gap later.
I also prefer reviewing progress at a regular moment, such as after a payday or before a new month begins. A short review can reveal whether the target needs adjusting. If an unexpected expense makes the original plan unrealistic, changing the goal is more sensible than abandoning the whole system. The app can organize that process, but it cannot decide which trade-offs are acceptable for my household.
This is one of the places where Wallet differs from a basic banking app. A bank application is usually strongest at showing account activity and balances. Wallet is more focused on interpretation: categorizing spending, thinking ahead, and connecting daily choices with a planned outcome. For someone who wants that extra layer, the separation is helpful. For someone who already gets everything needed from a bank’s budgeting tools, Wallet may feel like another place to maintain.
Where it compares with spreadsheets and simple notes
A spreadsheet gives me flexibility, but it also asks me to design the system, maintain formulas, and decide how information should be presented. That can be excellent for a person who enjoys building a custom financial model. It is less appealing when I want to record a purchase quickly and return to my day. Wallet offers a more guided structure, so I spend less time constructing the framework and more time using it.
A notes app is faster for a rough list, but it becomes difficult to answer questions over time. Searching for “groceries” in a long stream of text is not the same as seeing a meaningful spending pattern. Wallet’s value comes from giving those entries a financial context rather than leaving them as isolated reminders.
Dedicated banking tools may be more convenient for people who want transactions to appear with minimal manual effort, depending on the setup they use. Wallet is a better match for someone who wants deliberate control over categories and planning. That control has a cost: the more carefully I want the records organized, the more attention I need to give them.
The friction I would consider before relying on it
Manual financial tracking can become repetitive. Even a well-designed app cannot make every small purchase feel interesting, and missed entries weaken the accuracy of later conclusions. If I tend to abandon routines after a few days, Wallet may start as an exciting project and then become another unfinished system.
There is also a risk of over-organizing. A detailed budget can create the illusion of control while taking too much time to maintain. I would resist creating categories for every tiny distinction unless that distinction leads to a decision. If two types of spending would be treated the same way, combining them may produce a more sustainable setup.
The paid structure deserves attention as well. Because purchases can range from a small amount to a much larger one, I would not choose based on the existence of an attractive extra alone. I would ask whether it solves a problem I already have, whether I will use it often, and whether the free experience has already shown that I can maintain the habit. Free access is valuable for testing the routine; paid value depends on repeated, practical use.
Another limitation is that organization does not equal financial advice. Wallet can help me see spending and plan around bills, but it does not remove the need to make judgment calls about debt, irregular income, emergencies, or competing household priorities. Someone looking for professional financial guidance should not mistake a tracking tool for a substitute for that support.
Who is likely to get the most from Wallet?
I would recommend Wallet to someone who wants more structure than a bank balance but less construction work than a personal spreadsheet. It suits people who are willing to record transactions, review categories, and use upcoming bills as part of their planning. It is especially practical for anyone whose money feels scattered across everyday purchases and recurring obligations.
It can also work well for couples or households that need a shared view of planned spending, provided everyone involved agrees on the categories and keeps the information current. The real advantage is not simply having a common list. It is being able to discuss priorities using the same picture of bills, spending, and savings rather than relying on different assumptions.
People with irregular income may appreciate the planning perspective, but they should use conservative estimates. A strong month should not automatically become the basis for a fixed commitment. I would build the routine around essential bills and a cautious view of available money, then treat unusually good income as a reason to strengthen savings rather than expand recurring spending immediately.
I would skip Wallet if I want completely passive tracking, dislike entering or reviewing financial information, or already have a banking service that provides the exact planning tools I use. I would also avoid paying for extras before I know whether I can keep the basic habit alive. In those cases, a simpler method may be more effective because consistency matters more than the number of features.
My way of testing it before spending money
I would start with one normal week rather than trying to rebuild my entire financial history. I would record regular purchases, add the bills that affect the next planning period, and look at whether the categories help me make decisions. This short trial reveals more than a long setup session because it tests the app under ordinary conditions.
Next, I would perform a weekly review with three questions: which category surprised me, which bill needs protection, and what amount can realistically move toward savings? If the answers are clear and the process does not feel burdensome, Wallet is probably earning its place. If I am spending more time adjusting categories than learning anything, I would simplify the structure before considering an in-app purchase.
I would also test an imperfect week. Real budgets include forgotten receipts, unusual purchases, and changes in plans. An app is useful when I can correct those records without losing confidence in the whole picture. This is a better test than entering neat sample transactions, because financial tools need to survive ordinary messiness.
My final recommendation
Wallet: Budget Expense Tracker is a convincing choice for people who want an organized view of spending, bills, and savings in one finance app. I like that the free starting point lets me evaluate the workflow before paying, and I find its strongest use case is forward planning: knowing what money is committed, what remains flexible, and whether a savings goal fits the month ahead.
Its main weakness is the same quality that gives it value. It asks me to participate. The app cannot produce a trustworthy budget from incomplete records, and more detailed organization is not automatically better. I get the best results by keeping categories practical, reviewing bills before discretionary spending, and treating savings as a realistic plan rather than a hopeful number.
With a 4.6 average and a large installed audience, it is clearly not an obscure experiment, but popularity should not replace a personal trial. I would begin with the free version, build a modest routine, and only then consider whether an in-app purchase adds enough lasting value. For a person who wants intentional money management and is prepared to keep the records current, I would recommend giving it a serious try. For someone seeking effortless automation or a very simple note-taking tool, I would skip it and choose the lighter option that is easier to maintain.
4.6
7.52K Reviews
Pros
- Quick expense entry makes daily spending easy to record.
- Clear charts help identify spending patterns at a glance.
- Useful budget categories keep finances organized.
- Recurring transaction support reduces repetitive manual entries.
- Simple interface is approachable for users new to budgeting.
Cons
- Some advanced tools may require a paid subscription.
- Manual entry can become tedious without bank synchronization.
- Limited customization may not suit complex budgeting systems.
- Accurate results depend on consistently recording every transaction.
- Currency or regional support may vary by device and location.


